RBI intervention and scheduled debt sales reshape market backdrop
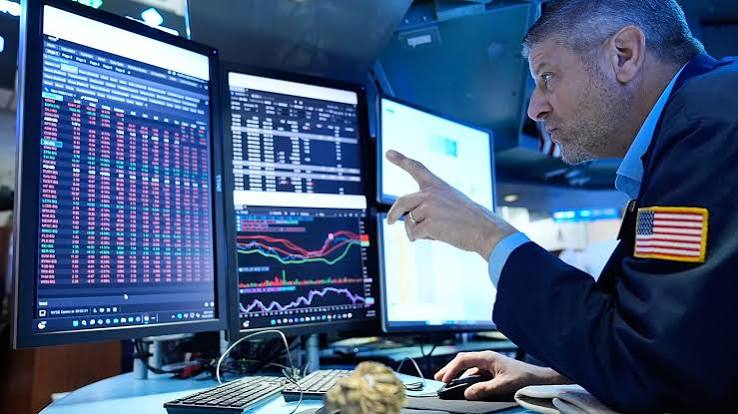
MUMBAI , India’s central bank reinforced its market support on September 28 as currency and bond markets grappled with higher global yields and elevated oil prices. The rupee closed marginally stronger on the day, but traders and strategists warned that the currency and sovereign yields would stay sensitive to shifts in oil markets, US interest-rate expectations and domestic liquidity operations.
Traders said the Reserve Bank of India had remained active in markets over recent sessions to dampen volatility, a trend that continued into September 28. The local unit ended the day with a modest gain, reversing some of the recent weakness that had pushed it near key round-number levels in front of month-end flows and data releases.
Why markets are volatile
Two broad forces have driven the recent turbulence. First, oil prices have risen back above the threshold that weighs on India’s import bill, adding pressure to the current account and prompting concerns about inflation and the central bank’s policy stance. Second, global government bond yields have climbed, driven by persistent US inflation surprises and expectations that the Federal Reserve could hold policy tighter for longer. Higher US yields typically weigh on emerging market currencies and make foreign investors more cautious about holding longer dated local bonds.
The combination has kept Indian government bond yields under upward pressure. Traders expect benchmark 10 year yields to remain within a range that reflects that tension, with attention focused on weekly debt supply and the central bank’s liquidity operations designed to mop up surplus cash from the banking system.
RBI tools and timing
Market participants said the RBI has been using a range of tools to manage both exchange-rate volatility and liquidity. These include outright sales of government securities through open market operations, sell buyback swaps and foreign exchange intervention via state banks. The central bank’s sequence of operations is aimed at both supporting the rupee when it comes under sharp downward pressure and at absorbing excess rupee liquidity that could stoke inflationary risks.
On September 28, participants also noted an unusually heavy calendar for debt operations. Dealers were focused on the absorption of fresh supply as well as on the Reserve Bank’s announced market interventions. The combination of new supply, rising global yields and ongoing FX support operations has been cited by dealers as the reason yields have moved higher in recent weeks.
Foreign flows and market sentiment
Foreign portfolio flows have been a second key battleground. Inflows driven by primary market activity have not always translated into broad purchases of existing equity or debt, leaving local indices and bond markets vulnerable to global risk aversion. Recent depository figures showed continuing churn in foreign portfolio investment through the month, with net sales in some sessions even as larger strategic inflows continued into primary issuances.
Analysts said that a full market recovery would likely require a sustained reversal of global risk premia, or a significant overshoot in the scale of foreign purchases compared with the steady drip of primary-market subscriptions. Until then, domestic markets will remain sensitive to external developments, particularly US data prints and crude oil price moves that influence both inflation expectations and the rupee.
What to watch next
Investors are entering a week heavy with domestic data and policy focus. Key dates on the calendar include industrial output and fiscal data releases, and the closing sessions ahead of the central bank’s next policy announcements. Internationally, US labour-market and core inflation readings remain principal triggers for moves in global yields and dollar strength, which in turn feed into rupee and Indian bond volatility.
Market participants said they will watch the central bank’s liquidity operations closely. If the RBI persists with supply-side bond sales and FX interventions to defend the currency, that will continue to drain cash from the banking system and put upward pressure on short and intermediate term yields. Conversely, any sign that global yields soften or oil prices retreat could provide temporary relief for both the rupee and government securities.
Why this matters
India imports a large share of its energy needs, so persistent high oil prices raise the import bill, widen the current account gap and complicate the central bank’s inflation task. At the same time, higher domestic bond yields increase borrowing costs for the government and corporations, with potential knock on to investment and growth. For policymakers, the challenge is to strike a balance between defending financial stability and avoiding actions that could entrench higher inflation or materially increase government borrowing costs.
For investors, the near term outlook is one of continued sensitivity. Currency and bond markets are likely to remain reactive to headlines around oil and US monetary policy, with domestic liquidity operations and scheduled debt supply shaping the longer end of the yield curve. Authorities have shown they are prepared to be active in markets, but the ultimate direction will depend on how global shocks evolve and whether those shocks abate in coming weeks.
Reporting from Mumbai. Analysis by market participants and fixed income strategists.